There’s a moment in entrepreneurship when everything looks golden: strong sales, good margins, a friendly pitch on Shark Tank, and every reason to expect “overnight success.” Then comes the hard truth: revenue does not equal profit, and growth alone doesn’t equal sustainability.
That is exactly the cautionary tale behind Springer. A company that hit $1.7 million in sales, yet somehow saw almost $1.6 million “disappear” from meaningful profit. What happened behind the scenes of this pet-product brand reveals some of the toughest lessons for any founder.
The Shark Tank Pitch & Promise
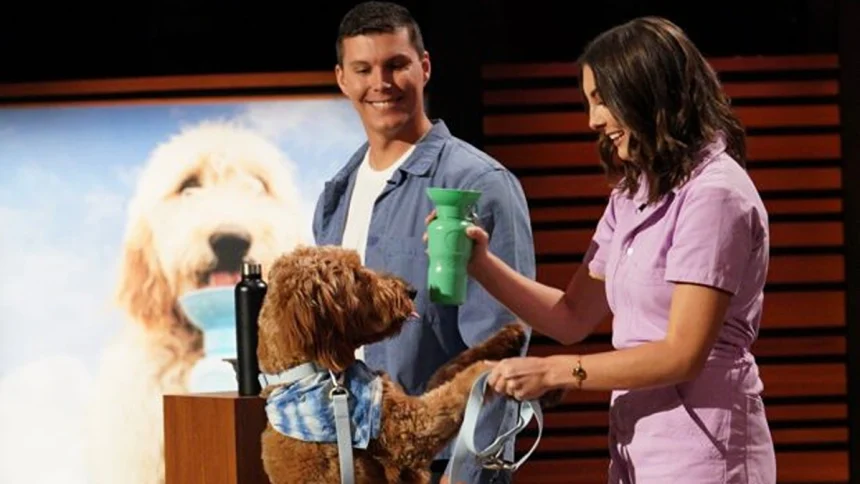
Springer is the brain-child of siblings Griffin Ross and Shannon Ross. They pitched their portable dog-water bottle with an integrated squeezable bowl on “Shark Tank Season 13 Episode 24.”
The concept was simple: when you’re walking your dog or travelling, carry less gear, just a bottle where the bowl is built-in. Moreover, the water flows back in when you’re done, and dogs stay hydrated on the go.
In their pitch, the Ross siblings sought $400,000 in exchange for 6% equity, valuing their company at about $6.67 million. The Sharks probed the product’s appeal, the patent strength, the manufacturing cost of about $3 a bottle, and margins claimed around 88%.
Finally, they accepted a deal from Shark Lori Greiner: $400,000 for 10% in preferred stock.
On the surface? A dream scenario: strong traction, a happy deal, a snapshot of success. In one year (2020), the company reported $1.7 million in sales.
Where Did the $1.6 Million Go?
Here’s where the story gets complex. Despite the $1.7 million revenue generated, the brand only made a profit of about $100,000 at that time. Thus, it clearly signals that $1.6 million was used in costs or unclear expenditures.
The Sharks raised knock-outs:
- Shark Robert Herjavec flagged high founder salaries, suggesting money was going out to the owners rather than being reinvested smartly.
- They asked, “What were you spending on? Inventory, marketing, operations, patents?” All valid questions.
- The equity ask (6%) was judged too small for the risk. That signaled to the Sharks that perhaps the founders hadn’t accounted for growth-funding needs.
In fact, the commonly cited breakdown showed high COGS (Cost of Goods Sold) plus large investments in branding, and minimal net profit relative to sales. The business plowed money back into the company.
While reinvestment isn’t inherently bad, it becomes an issue when transparency around costs, path to profitability and unit economics is weak.
Lessons from the Numbers
What can founders take away from the Springer case?
Understand the Gap Between Revenue and Profit
Hearing that they did $1.7 million in sales sounds impressive. But if you only made $100K in profit, you need to ask: why? Is it because of high costs, low pricing, or reinvestments? Without understanding unit economics, the headline number fades.
Cost Structure Matters
Springer claimed the bottle cost about $3 to make and sold it with an 88% margin. Yet margins on paper often don’t reflect real-world costs, including returns, shipping, warehousing, marketing, patent enforcement, and founder compensation. Your gross margin may look fine, but your net margin may tell a different story.
Founders Vs Reinvestment
The Sharks flagged the high salaries for founders. When owners pay themselves early, it can raise questions: Are you building a business or paying yourself? Transparent compensation and clear reinvestment plans matter.
Ask Realistic Equity
Springer asked for only 6% equity for a $400k investment. The Sharks balked because that equity was small relative to risk, growth capital and the scale required. If you’re going to ask for money, offer a share that aligns with anticipated capital and risk.
Protect Patents, But Don’t Overpay Yourself
Springer had eight patents and spent heavily on IP. But if IP is your moat, you still need operational execution, marketing, logistics, and brand building. Thus, those cost money, too. Having identity but lacking execution is risky.
What Happened to Springer After Shark Tank?
According to updates, Springer has continued to operate. The product remains available on Amazon and in independent pet boutiques. The brand is still alive.
However, there’s no evidence that the company has dramatically exploded into a giant enterprise—rather, it seems to be growing steadily, but with caution.
Some of the key questions still remain, like whether the investment from Lori has been finalized, whether returns are improving, what new products or categories are being launched, and whether margins have improved.
For the founders and for early-stage entrepreneurs, the Springer story gives a realistic view. Though with strong product and market fit, even with TV exposure, execution and cost control still win the day.
Why We Should Still Be Rooting for Springer
Despite the caution, Springer isn’t a failure story. Some positives:
- They found a real consumer pain point: traveling dog owners.
- They built a patent-protected product and launched successfully in the market.
- They secured a deal on Shark Tank, which is a major visibility boost.
- They’re still in business years later. For a product company, survival and sustained operations are wins in a crowded landscape.
The question is: can they turn revenue growth into margin improvement and sustainable scale? That remains the next phase.
Conclusion
Many entrepreneurs strive for that headline. But the real story, the more impactful one, is what happens after you hit that milestone. For Springer, the fact that $1.6 million of revenue seemingly dissipated into costs, reinvestments, and overhead is a lesson, not a defeat.